DGII raises vehicle registration sticker fees for 2026-2027


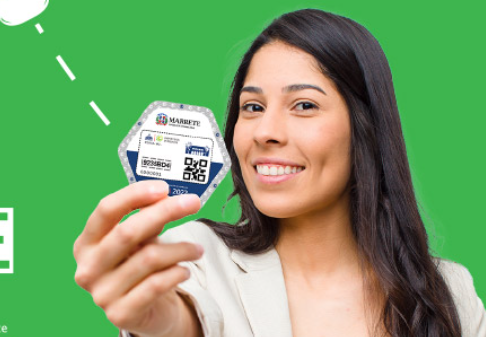
Santo Domingo.- The General Directorate of Internal Taxes (DGII) has increased the rates for the Vehicle Circulation Tax (ICV), commonly known as the vehicle registration sticker, for the 2026-2027 period.
Under Resolution No. DDG-AR1-2026-00009, vehicles manufactured up to and including 2021 will pay RD$2,000, while models from 2022 onward will pay RD$4,000. The new rates represent increases of RD$500 and RD$1,000, respectively, compared with the previous fees of RD$1,500 and RD$3,000.
The renewal period begins October 29, 2026, and runs through January 31, 2027. The DGII said the fixed rates had not been updated since 2016 and that the adjustment takes into account the accumulated evolution of prices, including inflation of 58.1%.
DGII projects RD$4.7 billion in revenue
The tax authority expects to collect approximately RD$4.7 billion from the vehicle circulation tax during the 2026-2027 period, up from the RD$3.525 billion projected for the previous cycle. This represents an estimated increase of RD$1.175 billion.
A total of 2,136,468 vehicles are eligible for renewal this year. Owners can complete the process through 55 authorized financial institutions with 845 branches nationwide, as well as DGII collection offices in Villa Vásquez, Montecristi, and Sánchez, Samaná.
Renewals are also available through the DGII website and DGII Móvil app. Digital channels will remain available until January 17, 2027.
Vehicle owners must present a legible, updated copy of the vehicle registration certificate in good condition.
Penalties for late renewal
Owners who fail to renew by January 31, 2027, will face a RD$2,000 surcharge for the 2026-2027 period.
Vehicles with unpaid fees from previous periods will also incur additional penalties. The surcharge is RD$2,100 for the 2025-2026 period and RD$3,100 for the 2024-2025 period and earlier, with both amounts including RD$100 for administrative cessation.
The DGII said the rate adjustment seeks to apply objective and verifiable criteria while maintaining a balance between tax collection efficiency and the fiscal sustainability of the State.